

Here we dispel some common myths about life insurance to help you make informed decisions about your cover.
Myth # 1 – Life insurance companies don’t pay claims
There’s a common perception that life insurance companies will do everything they can to avoid paying claims.
In fact, 92% of all life insurance claims are paid in the first instance¹.
As long as you fulfil your duty of disclosure when you apply for cover, and you’re covered for the medical condition you’re claiming for, you can be confident your claim will be paid.
Myth # 2 – I’m young and don’t have kids or a mortgage, so I don’t need it
Life insurance isn’t all about providing for debts and dependants. It’s also about looking after yourself.
Think what would happen if you became ill or disabled and couldn’t work. If you didn’t have income protection, you’d have to find another way to supplement your income – through friends or family. Having income protection means that you are more likely to be able to manage on your own.
There are benefits to applying for life insurance when you’re young and healthy. It’s generally cheaper and it means you don’t have to worry about getting cover later if your health changes (see myth #3).
Myth # 3 – I won’t be covered if my health changes
Once you start your cover, what you are covered under your life insurance for won’t change – even if your health declines.
In fact, you generally don’t even need to tell your insurer about a change in your health unless you intend to make a claim.
Myth # 4 – You have to do lots of medical tests to get covered
Some life insurance products sold through financial advisers require some medical tests before you get covered, but it may be as simple as one blood test and a GP examination.
- If you have an existing medical condition, you may be asked to provide extra information about your condition and insurers will generally write to your doctor for a report rather than require tests
- You generally won’t be covered for pre-existing conditions, so it’s important to establish upfront what those pre-existing conditions are. It’s important to answer all questions accurately upfront so any pre-existing conditions can be reviewed by your insurer for any impacts to your cover or ability to obtain cover.
- That way you know exactly what is and isn’t covered under your policy.
Myth # 5 – I’ll be stuck paying for cover I don’t need
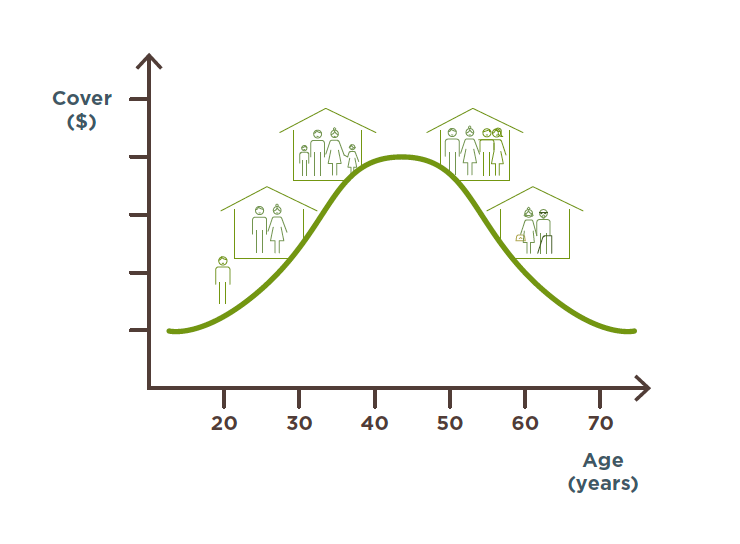
Life insurance is designed to change as your life changes, as your cover needs can vary significantly over your lifetime.
An example may be when taking out life insurance when getting married. You may want to increase your cover if you have children or increase your mortgage. But similarly you may want to reduce your cover if your children have grown up or you’ve paid down your debts.
Your financial adviser can help you work out how much cover you need at any given time, to make sure you’re not paying for any cover you don’t need.
Myth # 6 – The cover in my super is enough
Over 70% of Australian life insurance policies – more than 13.5 million separate policies – are held through superannuation funds*.
While this cover is great to have, many of these policies only provide the minimum level of cover employers have to offer, which isn’t enough for most people.
In fact, Rice Warner* estimates that the median level of cover in superannuation meets is only 60% of needs for life cover (or just 38% for families with children), 13% for TPD cover and 17% for income protection.
*Insurance through superannuation, 2016, www.ricewarner.com/insurance-through-superannuation/
Want to know more?
If you’d like to discuss any of the content in this article and how it may apply to you, please call our office on (08) 8208 4777 or book an appointment online with our Director of Financial Planning.
Miki Sato
6 years agoHi, looking to get an quote for income protection.